We receive the invoice from the garage, we declare the claim, and then, surprise: Macif withholds several hundred euros from the compensation. The deductible is often discovered at the worst moment, when it hasn’t been anticipated at the time of subscription. Understanding how the Macif comprehensive car deductible works helps avoid the gap between what we expect and what we actually receive after an accident.
Macif Deductible: What Happens After a Responsible Claim
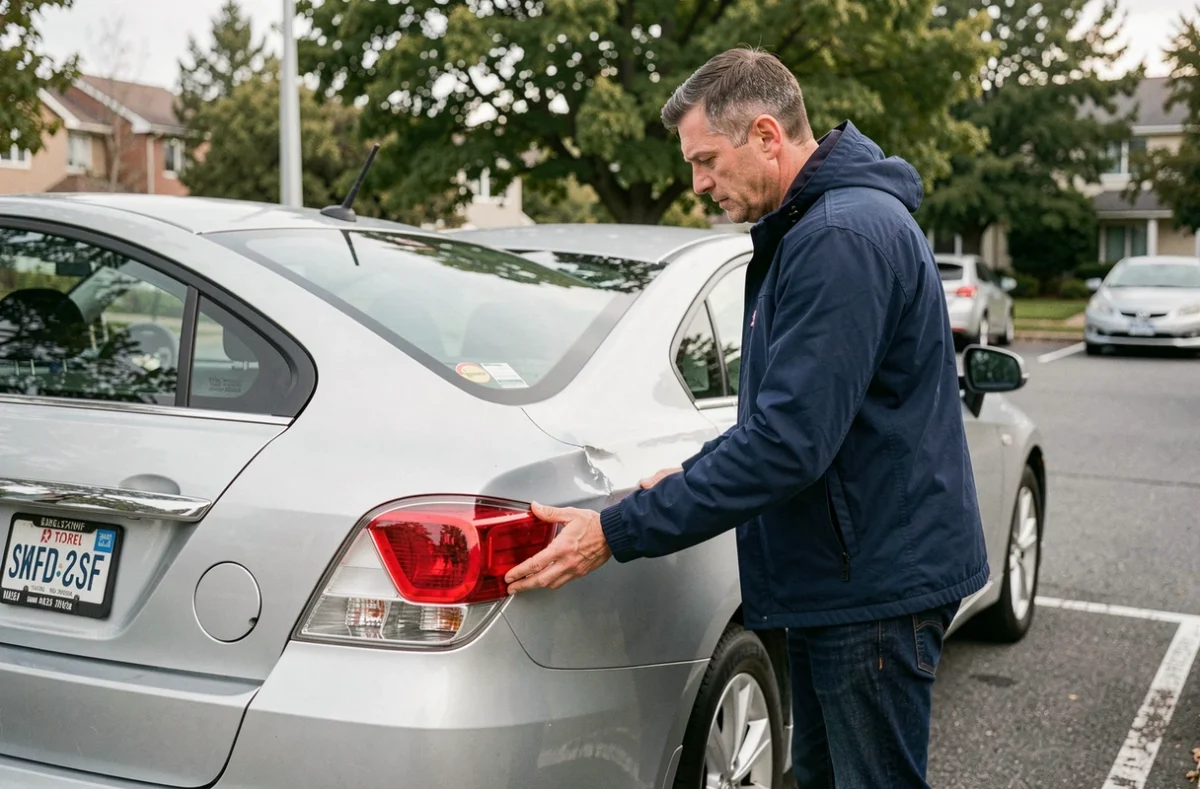
Let’s take a classic case. We hit a pole while maneuvering in a parking lot. The damage to our vehicle is estimated at 2,500 euros. With a comprehensive plan (called Protectrice or Premium at Macif), the damage to the vehicle is covered, but Macif deducts the deductible before paying the compensation.
The deductible corresponds to the amount that remains our responsibility. It applies every time we are responsible for the claim or when the third party is not identified. If we are not responsible and the third party is identified, no deductible is withheld.
In practice, we do not “pay” the deductible in the strict sense. We do not write a check. Macif subtracts it directly from the amount of the compensation paid to the repairer or to us. If the repair costs less than the deductible, we receive nothing at all.
To know in detail the amounts and conditions that apply, information about the Macif comprehensive car deductible allows us to pinpoint the thresholds according to the guarantees subscribed.
Amount of the Macif Car Deductible: Why It Varies from Contract to Contract
We often read about “average” car deductible amounts, but at Macif, as elsewhere, the amount depends on the chosen plan and the relevant guarantee. The deductible for glass breakage is not the same as for collision damage or theft.
Several parameters cause the amount to vary:
- The chosen plan: the Macif auto range goes from Economique (basic third-party) to Protectrice or Premium (comprehensive). The broader the coverage, the more detailed the deductibles are by type of claim.
- The type of claim: responsible collision, theft, attempted theft, glass breakage, natural disaster, each can have a distinct deductible threshold listed in the specific conditions.
- The driver’s profile: a young driver or a driver with a penalty may face a higher deductible compared to a driver with a bonus.
- The deductible buyback options: Macif offers options that reduce or eliminate the deductible on certain guarantees, for a higher premium.
To find the exact amount that concerns us, we consult the specific conditions of our contract (the personalized document, not the general conditions). The guarantee table details each applicable deductible, guarantee by guarantee.
The Case of Glass Breakage at Macif
Glass breakage is the most common claim, and the associated deductible often surprises. At Macif, the glass breakage deductible can vary depending on whether it is a replacement or a simple repair. Some recent comparisons show that the Macif glass breakage deductibles are in the lower average of the market for comprehensive plans, but feedback varies on this point depending on profiles and chosen options.
Macif Deductible Buyback: When the Option is Worth the Cost
The deductible buyback involves paying an additional annual premium so that Macif no longer withholds (or withholds less) deductible in the event of a claim. On paper, it is tempting. In practice, the calculation deserves attention.
The deductible buyback is only profitable if we declare at least one responsible claim during the covered period. If we drive for several years without an incident, the extra premium paid for the buyback is lost.
For a driver with a bonus who parks in a closed garage and drives little, the buyback often represents a disproportionate extra cost. For an urban driver who parks on the street, exposed to bumps and theft, the option changes the game. It is recommended to compare the annual buyback amount with the deductible amount we would pay in the event of a claim, and then honestly assess the likelihood of an incident.
Deductible and Bonus-Malus: Two Distinct Mechanisms
Frequent confusion: the deductible and the bonus-malus coefficient have nothing to do with each other. The deductible is an amount deducted from the compensation. The bonus-malus modifies the annual premium based on the claims history. A responsible claim triggers both simultaneously: we pay the deductible on the compensation, and we suffer a penalty on the next premium.
Buying back the deductible does not protect against the penalty. The impact on the reduction-increase coefficient remains the same, whether the deductible is bought back or not.
Comprehensive Premium at Macif in 2026: Positioning the Deductible in the Overall Budget
The Macif comprehensive plan (Protectrice or Premium) is positioned at the lower end of the market according to recent comparisons, with a premium around 30 to 40 euros per month for a bonus profile. Macif remains among the top of the cheapest mutual insurers in the comprehensive segment, even though auto premiums have generally increased in recent years across the sector.
This pricing competitiveness has a downside: Macif deductibles are not the lowest on the market for every guarantee. An insurer that charges more for the premium may offer lower, or even zero, deductibles. The real trade-off is between the monthly premium and the amount we are willing to bear in the event of a claim.
With over 5 million members and a third of the portfolio in auto insurance, Macif remains one of the major players in the market. The auto contract has been the mutual’s historical product since 1960, which translates into well-established claims management processes, even if insured feedback sometimes points to variable compensation times.
The key point to remember before subscribing: the deductible is not a flaw in the contract, it is a lever. The higher the deductible we accept, the lower the premium. Conversely, reducing the deductible costs in annual premium. At Macif, as with any insurer, it is advisable to read the deductible table in the specific conditions before signing, not after the first bump.